
Transfer Pricing Consultants in Dubai, UAE
FTA-Registered & Regulated Tax Agent
Transfer Pricing Services in UAE for Groups With Related-Party Dealings
If one company in your group sells to, lends to or charges a fee to another, the Federal Tax Authority expects that price to match what independent businesses would agree. That’s the arm’s length principle in Article 34 of the Corporate Tax Law, and it applies whatever your size. Our transfer pricing consultants in Dubai set those prices, write down how they were set, and defend them when the FTA asks.
- ✓ Related-party and connected-person transactions mapped and priced
- ✓ Transfer pricing disclosure form prepared with your Corporate Tax return
- ✓ Master File, Local File and benchmarking for groups above the thresholds
- ✓ FTA audit and Advance Pricing Agreement support
FREE CONSULTATION
What is transfer pricing in the UAE?
Transfer pricing is how a business prices its transactions with related parties, such as group companies, and with connected persons, such as owners and directors. Under Federal Decree-Law No. 47 of 2022, those prices must be at arm’s length. Businesses with revenue of AED 200 million or more, or in a multinational group with consolidated revenue of AED 3.15 billion or more, must also keep a Master File and a Local File (Ministerial Decision No. 97 of 2023).
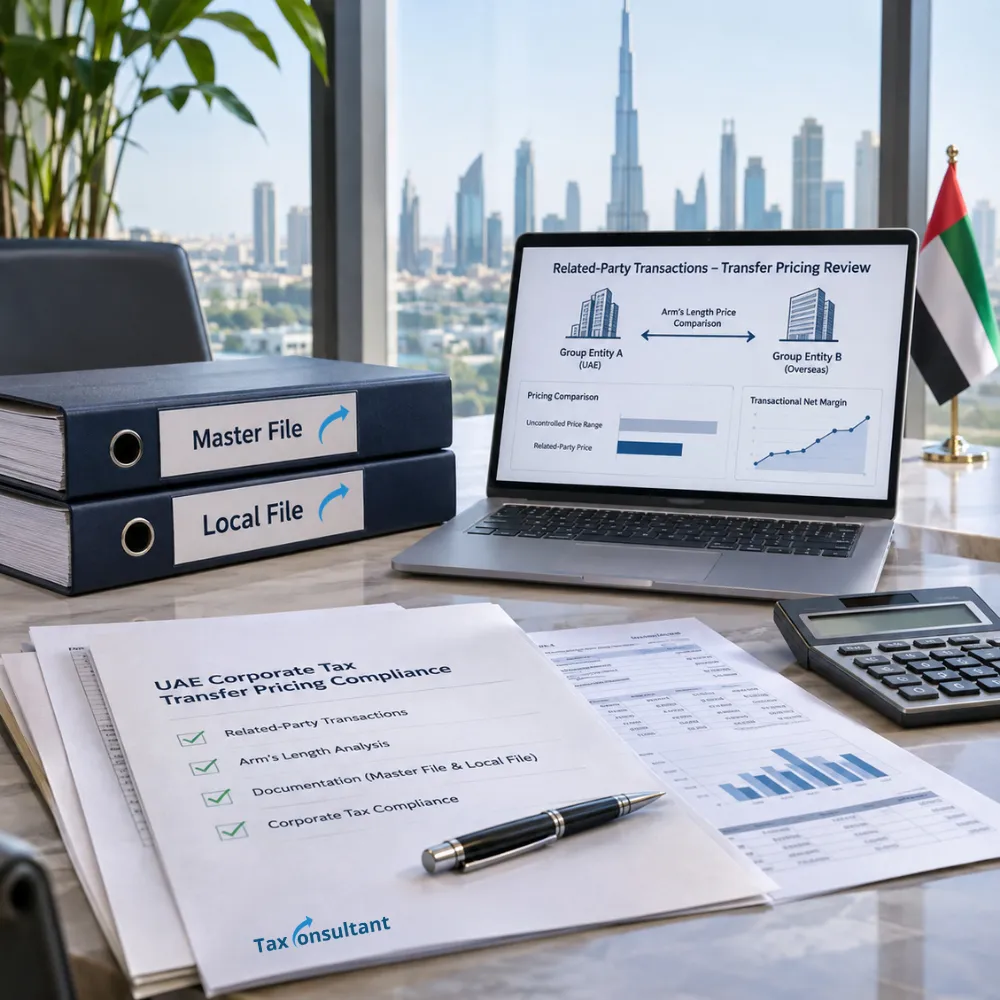
UAE Transfer Pricing Rules Under the Corporate Tax Law
Four articles of Federal Decree-Law No. 47 of 2022 do most of the work:
- Article 34 requires related-party transactions to meet the arm’s length standard, using one of five OECD-aligned methods: comparable uncontrolled price, resale price, cost plus, transactional net margin or transactional profit split
- Article 35 sets out who counts as a related party
- Article 36 limits deductions for payments to connected persons, such as owners and directors, to market value
- Article 55 covers the disclosure form and the Master File and Local File
Ministerial Decision No. 97 of 2023 sets the thresholds for the Master File and Local File. The FTA’s Transfer Pricing Guide (CTGTP1) explains how it expects the methods and documents to work in practice. In December 2025, the FTA added its Advance Pricing Agreements Guide (CTGAPA1).
Transfer Pricing in UAE: What Applies at Each Level
| Obligation | Who it applies to | When |
|---|---|---|
| Arm’s length pricing | Every taxable person with related-party or connected-person transactions | Every transaction, every tax period |
| Transfer pricing disclosure form | Related-party transactions above AED 40 million in total (categories above AED 4 million listed), or payments above AED 500,000 to a connected person | With the Corporate Tax return |
| Master File and Local File | Revenue of AED 200 million or more in the tax period, or a multinational group with consolidated revenue of AED 3.15 billion or more | Kept for each tax period; given to the FTA within 30 days of a request |
| Advance Pricing Agreement | Optional; generally for covered transactions of AED 100 million or more per tax period | Domestic unilateral APAs accepted since 30 December 2025 |
Free zone and mainland companies in the same group are a common blind spot. A Qualifying Free Zone Person pays 0% on qualifying income, so the FTA looks closely at what it charges its mainland sister companies.
Transfer Pricing Documentation Requirements
What you need depends on your size and on how much you deal with related parties.
Advance Pricing Agreements in the UAE
An APA lets you agree the pricing method for specified related-party transactions with the FTA before you file, so the question isn’t reopened in an audit. The FTA has accepted applications for unilateral APAs on domestic transactions since 30 December 2025. For domestic dealings, they are meant for cases where the two sides are taxed differently, for example where one is a Qualifying Free Zone Person. Cross-border APAs are being phased in, and the FTA announces when they open.
The general threshold is AED 100 million of covered transactions per tax period. The FTA fee is AED 30,000 for a first application and AED 15,000 for a renewal or amendment (Cabinet Decision No. 174 of 2025).
Where Transfer Pricing Goes Wrong
The usual problem isn’t a missing file. It’s a price nobody can explain. Examples: a management fee set at a round number years ago, a shareholder loan with no interest, or a free zone company buying from its mainland sister at a margin nobody tested. If the FTA moves the price to arm’s length, taxable income moves with it, and Corporate Tax follows on the difference. Payments to owners and directors are the other trap. Anything above market value isn’t deductible.
Our Transfer Pricing Services in Dubai
Our transfer pricing advisory in the UAE starts with the price itself and runs through to the audit:
- Transfer pricing policy design and intercompany agreements
- Benchmarking studies for goods, services, loans and royalties
- The transfer pricing disclosure form in your Corporate Tax return
- Master File and Local File preparation
- FTA queries and Corporate Tax audits
- Advance Pricing Agreement pre-filing and applications
Our consultants are FTA-registered tax agents. The same team prepares your Corporate Tax return, so the disclosure form, the files and the return tell the same story. The team has advised UAE businesses since 1985.
Related services: Corporate Tax in Dubai · Corporate Tax return filing · Corporate Tax registration · Corporate Tax audit
Frequently Asked Questions
What is transfer pricing under UAE Corporate Tax?
Who must prepare a Master File and Local File in the UAE?
Do smaller businesses need to follow transfer pricing rules?
What is the transfer pricing disclosure form?
Who counts as a connected person?
What is an Advance Pricing Agreement in the UAE?
What happens if the FTA disagrees with my transfer price?
Related Blogs
 March 16, 2026
Corporate Tax Planning in Dubai: A Complete Guide
Quick Answer Corporate tax planning in Dubai means structuring a business around three fixed numbers: the 0% rate...
Read Article March 2, 2026
Benefits of Hiring an FTA-Registered UAE Tax Agent Explained
Quick Answer A UAE Tax Agent is a professional registered with the Federal Tax Authority (FTA) who can...
Read Article December 24, 2025
Transfer Pricing Non-Compliance and Your UAE Corporate Tax Bill
Quick Answer Transfer pricing non-compliance under UAE Corporate Tax carries three distinct costs. First, the FTA can adjust...
Read Article December 24, 2025
The Arm's Length Principle in UAE Transfer Pricing: 5 Methods
Quick Answer The arm's length principle requires that transactions between related parties or connected persons produce the same...
Read Article